Reporting Rent Payments to Credit Bureaus: A Guide for Landlords, Property Managers, and Renters
For most renters, twelve months of on-time payments still leave no trace on a credit report, even as reporting rent payments to credit bureaus becomes more common. TransUnion’s 2025 rent reporting survey found that 13 percent of consumers had rent payments reported to credit agencies in 2025, up from 11 percent in 2024. That leaves a wide gap between what renters pay reliably and what lenders can see. Property owners and managers hold the data that closes it, and renters increasingly expect them to use it.
Learn how reporting rent payments to credit bureaus helps tenants build credit and how landlords and property managers can report rent responsibly. This guide explains how rent reporting for credit works, how tenants can get their payments reported, and how owners and managers can report on-time payments (and, where appropriate, non-payment) while staying inside the rules.
The short answer: Rent shows up on a credit report only when someone sends the payments to a credit bureau. Tenants can do this through a rent reporting service or a program like Experian Boost, and landlords or property managers can do it through a reporting service or property management platform that furnishes data to Experian, Equifax, and TransUnion. Reported on-time payments can help tenants build credit, while reported late or unpaid rent can hurt, so accuracy and consent matter on both sides.
What is rent reporting?
Rent reporting is the practice of sending a tenant’s monthly rent payment history to one or more of the three national credit bureaus so it can appear on their credit reports. It is also called rent credit reporting, rental credit reporting, or rent payment credit reporting, and the terms describe the same process. Because landlords are not lenders, rent payments are not included in credit files by default.
Two variants matter for how a program is designed:
- Positive rental payment reporting: Only on-time, complete payments are reported. This is the model California requires landlords to offer under AB 2747, covered below.
- Full-file reporting: Both on-time and late payments are reported, so missed rent can lower a credit score as well as on-time rent raising it.
Consumer rent reporting can also run in two directions. A landlord or property manager can report on behalf of all residents, or a renter can enroll individually and have a third-party service verify the payments. Both routes end at the same place: a tradeline on the tenant’s credit report.
Does paying your rent build credit?
Paying your rent builds credit only when the payments are reported to a credit bureau. Rent on a credit report is the exception rather than the rule, because landlords are not lenders and the bureaus never receive the payments by default.

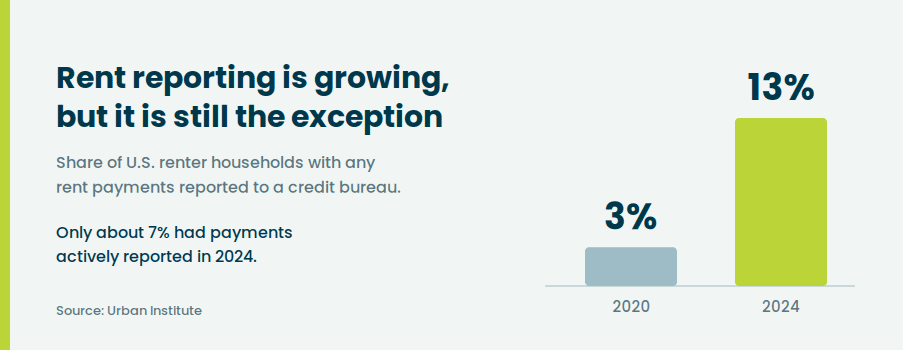
The gap is shrinking. The Urban Institute found that the share of renter households with any rent payments reported grew from about 3 percent in 2020 to about 13 percent in 2024, though active reporting reached only nearly 7 percent. When payments are reported, the results tend to be positive: in the TransUnion survey, 79 percent of renters with reported payments saw their credit scores increase. Credit score improvement through rent reporting is not guaranteed, but it is common.
Building credit with rent payments works best for people with thin or limited credit files, because a year or more of consistent payments gives a scoring model something to measure. Renters who want to build credit with rent typically take one of these approaches:
- Enrolling in a landlord-offered rent reporting program at lease signing
- Signing up for a third-party rent reporting service on their own
- Adding qualifying payments through Experian Boost, described below
- Asking a mortgage lender to consider rent history directly during an application
Which credit scores count rent payments?
Newer scoring models count reported rent, while older ones do not. myFICO states that since 2014, FICO has included reported rental data in all new versions of its scores, including FICO Score 9, FICO Score 10, and FICO Score 10 T. The same page notes that reported rental payments do not affect the older FICO versions currently used for many mortgages.
The mortgage market is moving in the same direction. The Federal Housing Finance Agency said in 2022 that FICO 10 T and VantageScore 4.0 take rent payment history into account, and it has since expanded lender access to VantageScore 4.0. Separately, Fannie Mae’s Desktop Underwriter can use 12 consecutive months of rent payments of $300 or more to improve a first-time buyer’s loan recommendation, and Fannie Mae reports that more than 21,000 applications benefited between September 2021 and May 2026.
The practical takeaway for tenants is that using rent to build credit pays off most with newer scores, and renters who want to boost credit with rent payments benefit more as lenders adopt them. For property owners, it means the data you furnish now has a longer shelf life than it did even three years ago.
How to report rent to credit bureaus as a tenant
Tenants can report rent payments to credit bureaus in three ways: through a landlord or property manager who offers reporting, through a paid or free third-party rent reporting service, or through Experian Boost. Rent reporting to build credit is available in each form, and the right choice depends on how you pay rent and whether your landlord already participates.
Here is how to report rent to credit, and how to add rent to your credit report:
- Ask your landlord or property manager first. Ask whether they will report your rent to credit bureaus. Many multifamily communities already offer rent reporting through their rent payment platforms, and enrollment is often a checkbox in the resident portal.
- Check Experian Boost. Experian Boost is free and can add qualifying online rent payments to your Experian file. You need three qualifying payments within the last six months, with at least one in the last three, and it does not apply if rent is already reported through Experian RentBureau.
- Compare rent reporting services. If your landlord does not report, a third-party service can verify your payments and report rent payment to credit bureaus on your behalf. Confirm which bureaus receive your data, what it costs, and whether it can include past payments.
- Check your credit reports. After a billing cycle or two, review your reports from all three bureaus to confirm the tradeline appears and the payment history is accurate.
Self-report rent payments to credit bureau accounts
Tenants who want to self-report rent payments to credit bureau files usually do it through a service that verifies the payments, since a bureau needs a reliable record behind each tradeline. If you pay rent in cash, by money order, or through a peer-to-peer app, ask a service whether it can verify those payments. Experian Boost, for example, covers qualifying payments only.
Rent reporting companies that report to all 3 credit bureaus
Not every service reports to Experian, Equifax, and TransUnion, so coverage is the first thing to check. A service that reports to only one bureau can leave a lender with a blank file if that lender pulls a different one. Before you enroll, confirm:
- Which of the three bureaus receive your data
- Whether the fee is monthly, annual, or one-time, and whether back-reporting costs extra
- Whether late payments are reported as well as on-time payments
- How you can pause or cancel, and what happens to the reported history afterward
What landlords should know about reporting to credit bureaus
Yes, a landlord can report to a credit bureau. Landlord credit bureau reporting is permitted as long as the information furnished is accurate and complete, and the landlord or property manager follows the Fair Credit Reporting Act (FCRA).
Bureaus generally receive data in a standard electronic format called Metro 2, and companies that furnish data have duties under the FCRA to correct and update it. Few individual landlords build that pipeline themselves. Most route data through a rent reporting service or a leading property management platform that already handles formatting, bureau connections, and dispute workflows.
The Consumer Financial Protection Bureau made its expectations plain in 2021, saying it would look carefully at whether landlords and property management companies furnish accurate information. The agency added that inaccurate rental information can unfairly block a family from safe and affordable housing. In practice, a rent report to credit bureaus needs clear lease language, consistent treatment of all residents, and a process for investigating disputes.
How to report a tenant to credit agencies as a landlord
Landlords and property managers can report tenants to credit agencies by enrolling in a rent reporting service, using property management software with built-in or integrated rent reporting, or sending unpaid balances to a collection agency. The first two methods report ongoing payment behavior, while the third reports a delinquent debt.
For landlords working out how to report tenant rent payments to credit bureau systems, the process typically looks like this:
- Decide what to report. Choose positive-only or full-file reporting and apply the same policy to every resident.
- Choose a reporting path. Compare rent reporting services and property management platforms on bureau coverage, pricing, and dispute handling. If your payments already run through a leading rent collection platform, check whether reporting is included.
- Update your lease and notices. Disclose that rent payments may be reported, explain what is reported, and give residents any opt-in or opt-out choices your state requires.
- Submit payments on a regular schedule. Consistent monthly reporting is what makes the data useful to scoring models.
- Monitor and correct. Reconcile reported balances with your ledger, fix errors quickly, and respond to disputes from residents or the bureaus.
Reporting tenants to credit bureau accounts for non-payment
Reporting tenants to credit bureau files for non-payment carries more risk than reporting positive history. Late payments reported through a rent reporting program are only as reliable as the ledger behind them, and disputes tend to involve disputed fees, partial payments, or amounts covered by assistance programs. The CFPB has flagged arrearages that include amounts already paid through relief programs, as well as fees prohibited by law, as areas of scrutiny.
When unpaid rent goes to a collection agency, the resulting collection account is a separate route with its own timeline. The CFPB notes that a credit reporting company generally can report most negative information for seven years. Because the consequences for a tenant are long-lasting, reporting a debt should follow a documented ledger, a clear lease basis, and a well-defined dispute process.
Why property owners and managers report rent to credit bureaus
Reporting rent to the credit bureaus pays off for owners and managers for one main reason: tenants pay more reliably when they know it counts. Nearly 80 percent of renters in TransUnion’s 2025 survey said they would pay on time when their payments are reported to credit reporting agencies, and 57 percent said they were more likely to rent from a property manager that offers payment reporting.
That gives reporting a place in both collections and leasing strategy:
- On-time payment incentive: Reported history gives residents a tangible reason to avoid late payments, which supports cash flow and reduces collection effort.
- Leasing appeal: Reporting is an amenity that helps a community stand out with credit-building renters.
- Negative reporting as a deterrent: For owners who choose full-file reporting, the prospect of a reported missed payment reinforces the on-time expectation, provided residents are told in advance.
Reporting works best alongside sound front-end practices. Resident screening that verifies credit, rental history, and income helps set the right tenants up for success, and reporting extends that visibility across the lease term.
When landlords should report rent and when to hold off
Report when the program is opt-in, the ledger is reliable, and the reporting path handles disputes. Hold off, or limit reporting to positive history, when accounting data is unreliable or when your state restricts what can be reported.
Use this checklist to decide:
- Report positive payments when: your rent ledger is reconciled monthly, residents can opt in with clear disclosure, and your platform or service can process disputes.
- Consider full-file reporting when: your lease language clearly discloses it, your state allows it, and your team can document every late or missed payment with accurate amounts.
- Hold off when: balances are frequently disputed, fees are inconsistently applied, or you cannot answer a resident’s dispute within the FCRA’s required timelines.
- Check state law first when: you operate in California or another state with rent reporting rules. California’s AB 2747 requires most landlords to offer tenants the option of positive rent reporting. It prohibits reporting delinquent rent, caps any tenant fee at the lesser of actual cost or $10 per month, and requires the offer at lease signing and at least annually.
Multi-state portfolios face the most complexity, since each jurisdiction can define what counts as reportable and what disclosures are required. That is a strong argument for standardizing on a platform that manages these rules centrally.
How much rent reporting costs and what it returns
Rent reporting can cost tenants nothing or a few dollars per month, while costs for landlords depend on the platform and how reporting is bundled. Experian Boost is free to consumers, and the Urban Institute noted that one small-landlord service charged $4.95 monthly to tenants who chose to participate. California caps landlord-charged fees at $10 per month.
Even small fees create barriers. The same Urban Institute research found that cost, awareness, and complexity kept many small-property tenants from opting in, and that most were unsure whether their rent was reported at all. For landlords, that suggests two things: absorbing or minimizing the fee raises participation, and clear resident communication matters as much as the technology.
The return for owners shows up in three places:
- Collections: Residents motivated to protect a reported record may pay earlier, reducing follow-up costs and late fees you would otherwise have to chase.
- Leasing: Reporting differentiates a community for renters who want credit-building benefits.
- Data: Payment history becomes a portfolio-wide dataset for forecasting delinquency and resident behavior.
For tenants, the return is a stronger file when it matters most. Reported rent can support applications for a first credit card, an auto loan, or a mortgage, especially for renters with limited credit history.
Rent reporting with MRI Software
Property management teams that already collect rent through a resident portal are well positioned to add reporting. MRI Engage Pay (formerly RentPayment) combines flexible payment options, including card, bank transfer, autopay, and cash, with rewards and rent reporting that builds residents’ credit histories. Because it integrates with multifamily property management software, payment data flows from the same ledger teams already use.
Running collections and reporting from one system supports the accuracy the CFPB expects and removes the manual work of building a separate reporting pipeline.
Rent reporting is becoming part of the standard resident experience
As newer scoring models and mortgage underwriting tools give more weight to rent history, the case for reporting rent payments to credit bureaus grows stronger for both sides of the lease. Renters gain a way to turn a monthly obligation into a credit-building asset, and owners gain a lever that encourages on-time payment. The organizations that treat rent reporting as an accurate, well-disclosed part of resident operations will be best positioned as adoption continues to climb. Learn more about how MRI Engage Pay can support rent collection and reporting across your portfolio.
Frequently asked questions about reporting rent payments
MRI Managed Services for Property Accounting
Accounting teams do more than balance ledgers. There’s AP/AR, closing, reconciliation, reporting, and many other tasks that keep your business moving – and all of it must be done right the first time. (No pressure.) Make your life easier with M…
