
Voice of the Commercial Tenant
Waldo Marcus, Director at TPN from MRI Software
A survey of 950 respondents across retail, office, industrial and mixed-use sectors, examining commercial tenant pressures, satisfaction, business confidence, rental escalation tolerance, lease renewal risk and technology adoption.
Waldo Marcus, Director at TPN from MRI Software
Key findings from South African commercial tenants
- Retail is the largest surveyed tenant sector at 39%, followed by office at 19%, other at 16% and industrial at 13%.
- Affordability dominates tenant pressure: high rental costs (32%) and high operating costs (14%) together account for 46% of challenges raised.
- Tenant satisfaction is stable but fragile: 40% rate their premises 4 or 5 out of 5, while 38% give a neutral rating of 3.
- Business performance remains under pressure: 42% report declining performance over the past year, compared with 29% reporting growth.
- Rental escalation tolerance is concentrated at the low end: 50.9% consider annual increases of 1-4% acceptable and 32.1% accept 5-7%.
- Lease renewal intent is positive but not secure: 54% are likely or very likely to renew, 27% are undecided and 19% are unlikely or very unlikely.
- Technology is a growth enabler: around two thirds of tenants report a positive impact from technology adopted in the past 12 months.
Foreword
The South African commercial real estate landscape is undergoing a period of transition. While the sector has shown remarkable resilience in the face of macro-economic volatility, the relationship between landlords and tenants is being redefined by new operational realities. TPN’s inaugural 2026 Voice of the Commercial Tenant Report is the first comprehensive survey of its kind to engage directly with the heartbeat of the industry: the tenants themselves.
By capturing the insights of 950 respondents across the retail, office, industrial and mixed-use sectors, this research moves beyond balance sheets to understand the qualitative and quantitative drivers of tenant behaviour. As economic and infrastructure challenges add to the financial strain of South African businesses, understanding the “why” behind tenant decisions has never been more critical.
The report provides a granular analysis of the commercial ecosystem, examining everything from business confidence and growth barriers to technology adoption and renewal intent. Our goal is to move the conversation between landlords and their commercial tenants from a transactional monthly cost mindset toward a proactive partnership model. By identifying the gap between current premises performance and tenant expectations, landlords and managing agents can better align their strategies to support a functioning, sustainable and growing economy.
About TPN from MRI Software:
TPN is the only credit bureau globally to specialise in tenant payment behaviour. As the creator of the world’s first rental payment profile, TPN provides the most comprehensive and up-to-date insights into tenant behaviour across South Africa’s residential and commercial property sectors. Its data is widely trusted by institutions including the South African Reserve Bank, commercial banks and industry bodies.
The tenant profile
Tenants can occupy a variety of categories. They may, for example, have a combination of retail, office and industrial lease premises within their rental portfolio.
The majority of tenants participating in the survey (39%) occupy retail premises, followed by office space (19%) and ‘other’ (16%). The latter includes entertainment, hospitality, shared office service spaces and data centres, amongst others. Due to self-classification, the ‘other’ sector may also include tenants occupying specialised offices and or industrial facilities. Industrial tenants represent 13% of the tenant population in this survey. The smallest space classification is storage (3%).
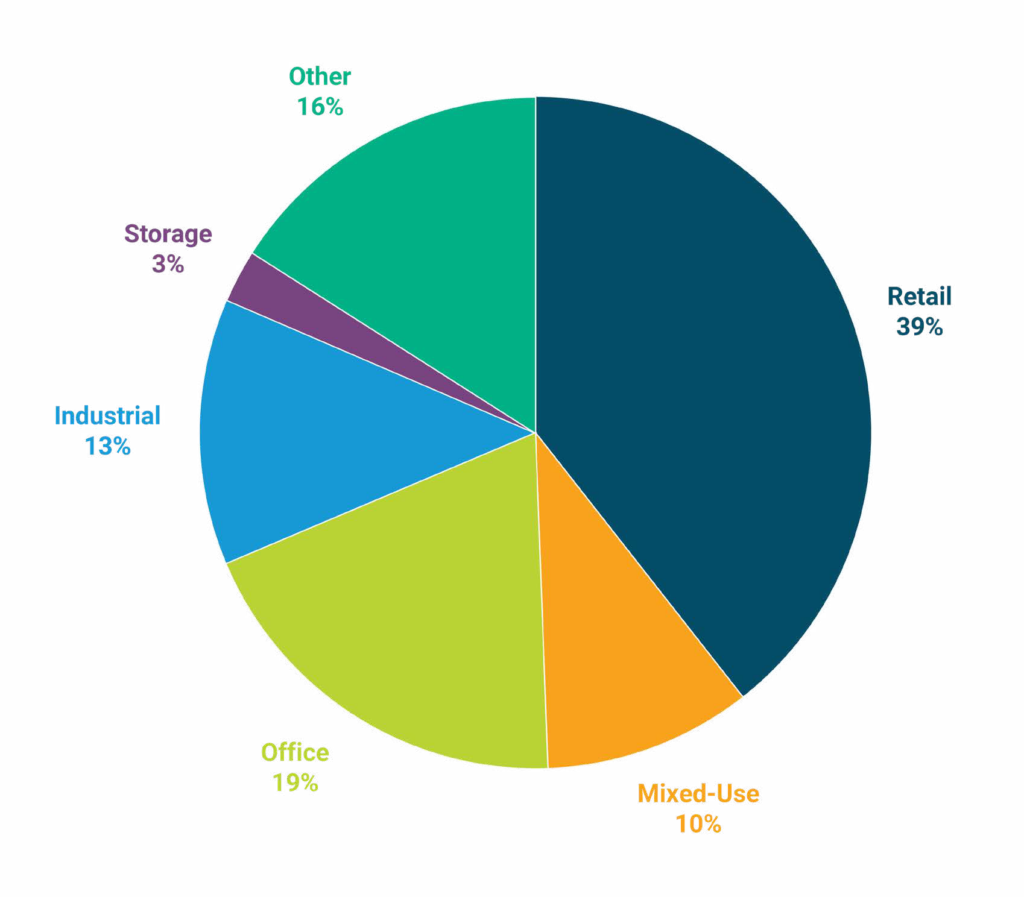
Image caption: Sector distribution
The commercial landscape is increasingly defined by smaller organisations, with a significant 93% of the tenant base maintaining a footprint of between one and ten premises. In contrast, organisations leasing more than 50 sites represent just 3% of the market.
Beyond the sheer volume of sites, the average footprint per premises provides insight into current market demand. A clear trend toward right-sizing is evident, with nearly half (47%) of all tenants securing their average space size between 100 and 500m². This is followed by the micro-occupancy segment, where 29% of tenants occupy premises of less than 100m². Just 14% of tenants occupy spaces between 501 and 1,000m² while 9% exceed 1,000m² per site on average.
Retail holds the largest share across all sectors in the sample, regardless of premises size. It is especially notable in spaces under 500m², where it constitutes a significant portion of tenants in both the less than 100m² and 100 to 500m² categories. Although the proportion of retail tenants declines as premises size increases, retail remains consistently represented across all size ranges, including those above 1,000m². Office tenants are most prevalent in the 100 to 500m² range, with smaller shares in premises under 100m² and decreasing representation in larger size categories. This suggests that office tenants tend to occupy mid-sized premises rather than very small or very large spaces. Industrial tenants display a more balanced distribution of premises sizes compared to retail and office tenants.
While the 100 to 500m² category remains the largest for industrial tenants, they also have a significant presence in smaller premises and in spaces exceeding 1,000m², indicating a wider spread across the sample. Mixed-use tenants are primarily found in small to mid-sized premises, with limited presence in those over 1,000m². The ‘other’ sector follows a similar trend, with the highest share in the 100 to 500m² category and decreasing proportions as premises size increases. Storage is the smallest sector in the sample, showing minimal and consistently low representation across all premises sizes.
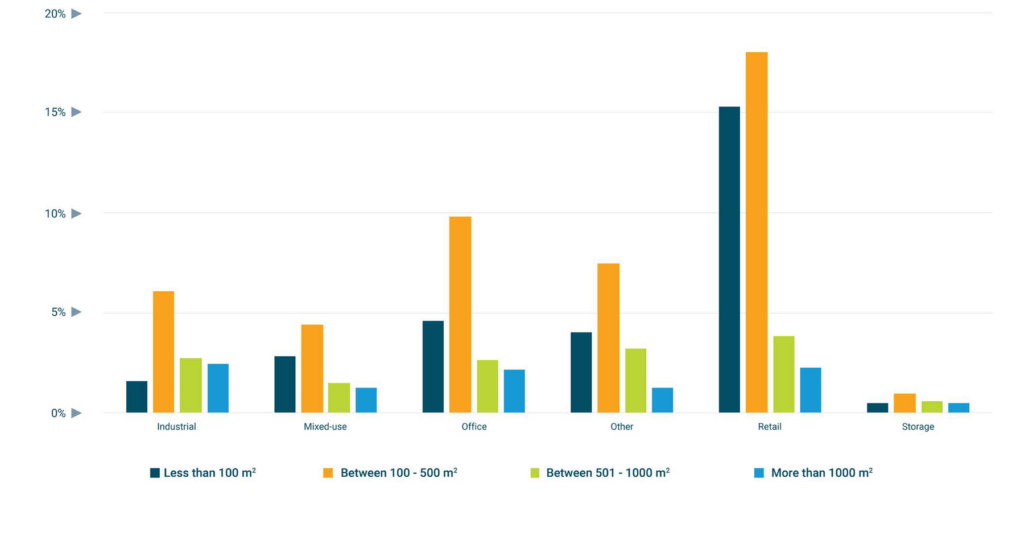
Image caption: Tenant sector by premises size
The survey reveals a diverse range of occupancy durations. The largest group, consisting of 27% of respondents, have occupied their current premises for one to three years, while 11% have occupied their premises for less than one year. Approximately 17% have been in their current space for three to five years. A significant proportion of tenants have been in their locations much longer, with 23% occupying their premises for over ten years and 22% for a period of five to ten years.
Overall, the data shows a wide distribution of occupancy lengths, balancing both newer tenants and those with long-standing presence.
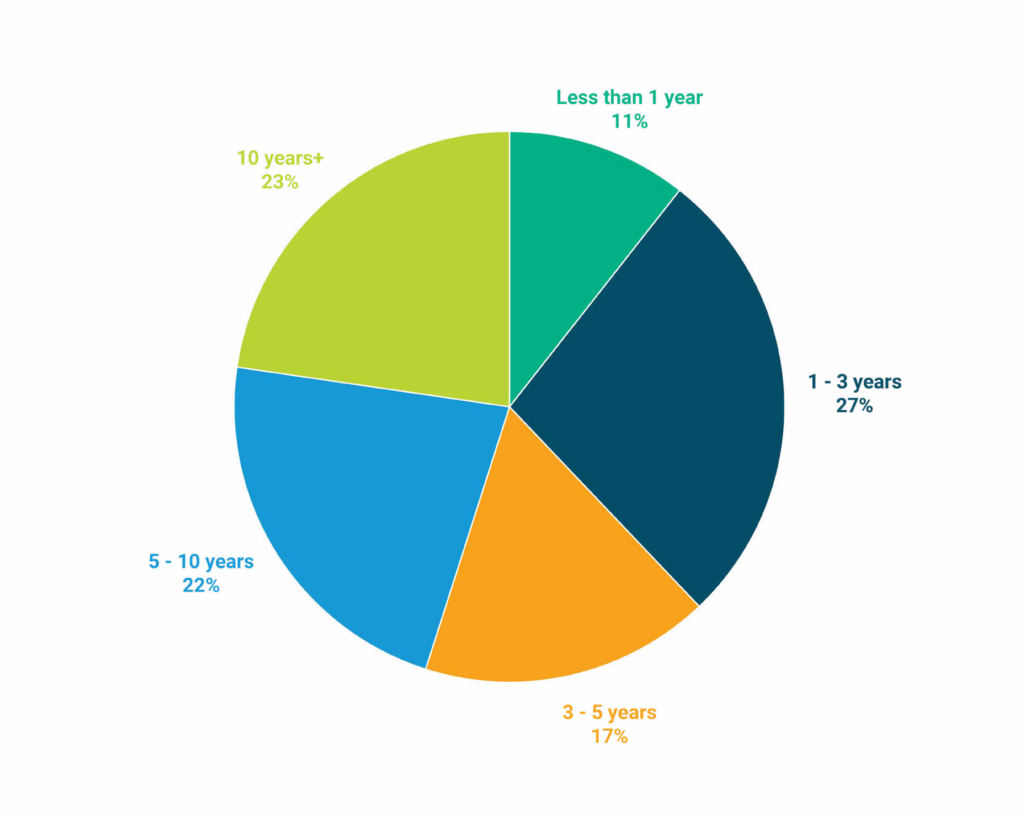
Image caption: Current lease occupation duration
Tenant pressures
The survey asked tenants to identify the top three challenges they experience in their current leased premises. The results highlight a clear set of pressures that shape the day to day tenant experience across all sectors. The most prominent challenge is cost pressure with 32% of respondents reporting that high rental costs and high operating costs (14%) together account for nearly half (46%) of all challenges raised. This shows that, for many tenants, the combined cost of renting and running a business from their premises is the single biggest challenge they face in their current occupation, outweighing all other issues.
The second biggest challenge concerns government, municipal or State dependencies. Challenges linked to load shedding and electricity supply (9%), poor infrastructure maintenance (8%), security concerns (8%) and municipal maintenance and service delivery (5%) account for around 30% of responses. Although these issues are largely outside tenants’ direct control, they do affect business continuity and operating conditions requiring resource allocation to mitigate risk.
The third challenge is access to customers, with a lack of foot traffic or customer access (8%) emerging as a key concern. Combined, these findings reveal that tenant experience is driven primarily by affordability, the reliability of public services and the broader operating environment surrounding leased premises.
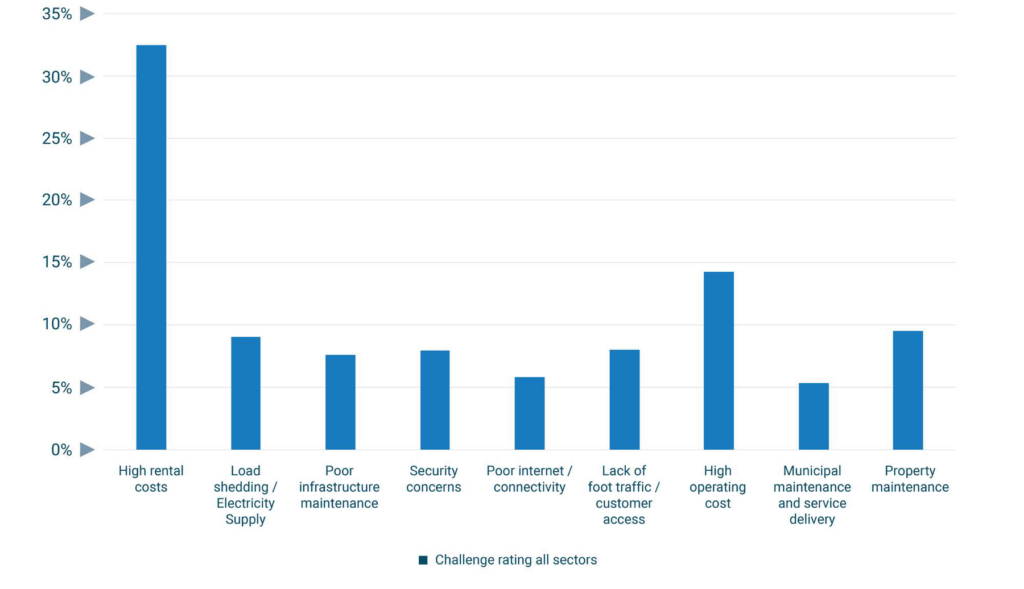
Image caption: Tenant challenges – all sectors
Operational hurdles
While high rental costs are ranked as the most significant premises challenge, non rental challenges vary by sector, highlighting the relationship between the type of premises tenants occupy and the challenges they experience most.
Across nearly all sectors, high operating costs are the most significant challenge. This is particularly evident among retail tenants (24%), office tenants (23%) and those in the ‘other’ category (19%), indicating that day to day operating expenses are a major pressure point across sectors.
Challenges linked to government, municipal or state dependencies show clear sector variation. Industrial tenants report the highest impact from load shedding and electricity supply issues (18%), reflecting the importance of reliable power for industrial operations. Storage tenants are most concerned about infrastructure and municipal service delivery, with poor infrastructure maintenance and municipal services both approaching 19%.
Property maintenance is consistently ranked high in the office (20%) and other sectors (18%), suggesting that building conditions and upkeep are real challenges in these environments. Improved facility management and preventive maintenance will be required to address these challenges, especially in the office sector, to enhance the tenant experience.
Surprisingly, security is only a moderate challenge across sectors, with its impact closely linked to the type of premises occupied. Retail and mixed use tenants report security concerns at around 10%, reflecting the exposure of customer-facing environments to theft, robbery, vandalism and other safety risks. In the industrial sector, 12% of tenants report notable security challenges, likely linked to larger premises, equipment and operational assets that require protection in exposed areas. In the office sector, 14% of tenants report elevated security concerns with storage showing the lowest reported impact, suggesting fewer direct security pressures in these environments.
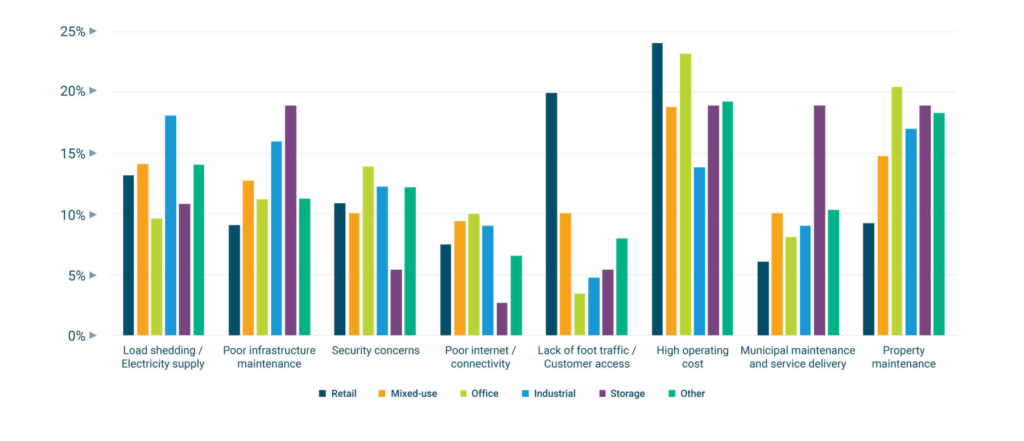
Image caption: Challenges by sector – excluding high rental cost
Tenant satisfaction metrics: Practicality over enthusiasm
Most tenants feel moderately positive about their leased premises. The largest share of respondents (38%) rated their experience at three out of five, indicating that their premises are acceptable and meet basic needs, although they do not exceed expectations. This suggests a sense of practicality rather than enthusiasm.
Encouragingly, a meaningful proportion of tenants rated their satisfaction as four or five, showing that a sizeable group (40%) is genuinely happy with their space and overall leasing experience. However, the relatively smaller share of “very satisfied” tenants (11%) highlights room for improvement.
Around one in five tenants selected ratings of one or two, signalling frustration or dissatisfaction. While this is not the majority, it is significant enough to warrant concern around defaulting and the non-renewal of their current lease agreements.
Despite the overall picture of stability, there are opportunities to improve everyday tenant experiences, including how to address current tenant challenges, and to shift more respondents from neutral into the satisfied category.
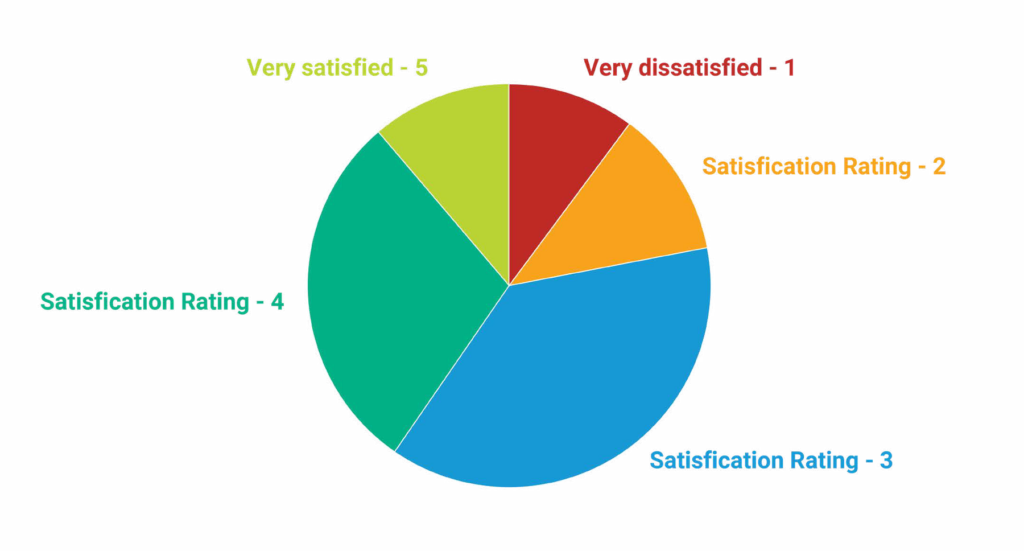
Image caption: Overall tenant satisfaction rating
Sectoral sentiment
Retail: Strong neutral concentration
Retail stands out for its elevated satisfaction rating of 3 out of 5 (neutral), at just over 40% of respondents. This is the highest single rating concentration across all sectors. Retail also shows a comparatively lower share of satisfied tenants (rating 4) at around 24% and a relatively small, very satisfied group (under 10%).
Interpretation: Retail tenants are not broadly dissatisfied, but confidence is fragile. The dominance of neutrality signals elevated renewal risk if trading conditions worsen.
Office: Skewed toward satisfaction
Office is a positive outlier at satisfaction rating of 4 out of 5, with 34% of tenants selecting this rating, the highest share at rating 4 across sectors. The office has a lower neutral share than retail and a modest dissatisfied segment at 11%.
Interpretation: Office tenants are generally content but not strongly loyal; satisfaction is present, yet not deep enough to absorb unpredictable changes in the market to remain loyal to the current space they are occupying.
Industrial: High satisfaction
Industrial shows a strong skew toward higher satisfaction, with around 33% at rating 4 out of 5 and a relatively higher very satisfied share (around 8-9%) than retail and mixed use. Dissatisfaction (ratings 1-2) is comparatively low.
Interpretation: Industrial is the most stable sector, with clearer value alignment between space and business needs.
Storage and ‘other’: Elevated very satisfied
Storage and ‘other’ sectors stand out with satisfaction ratings of 5 out of 5, with approximately 17% (storage) and 18% (other) of tenants reporting very high satisfaction, the highest among all sectors.
Interpretation: Although smaller in size, these sectors show strong positive sentiment, likely reflecting simpler use cases and clearer value propositions.
Mixed use: Even but unremarkable
Mixed use does not show a strong spike at any single rating. Satisfaction is spread fairly evenly across neutral and satisfied responses, with no dominant outlier.
Interpretation: Mixed use outcomes appear asset specific rather than sector driven.
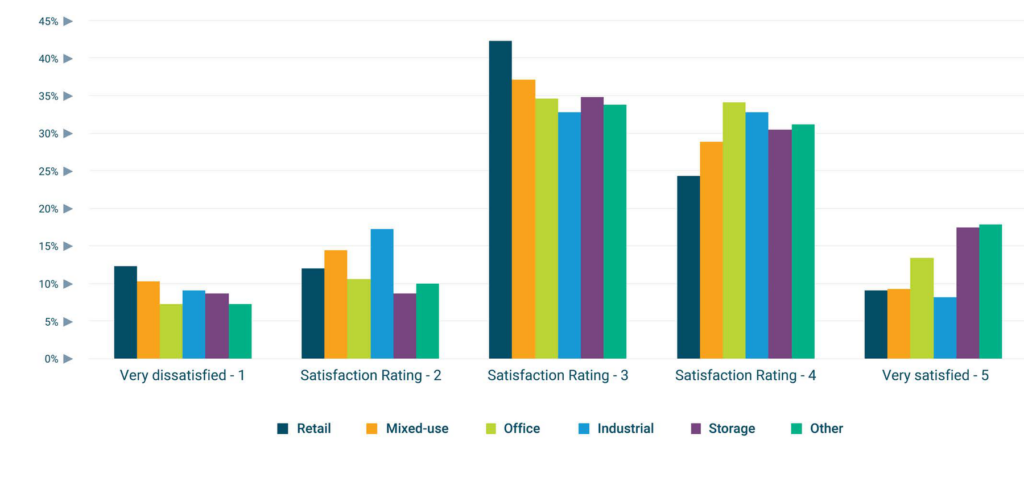
Image caption: Commercial tenant overall satisfaction by sector
Economic outlook and confidence indicators
The economic outlook varies meaningfully by sector, reflecting how different tenant groups perceive near term business conditions and their ability to absorb ongoing cost pressures, as well as their business performance in meeting their rental obligations, expansion or restructuring of their space requirements. While overall sentiment across all sectors is cautiously balanced with 32% of tenants reporting a neutral outlook, 31% somewhat positive and 12% very positive, sector level differences highlight where confidence is strengthening or weakening.
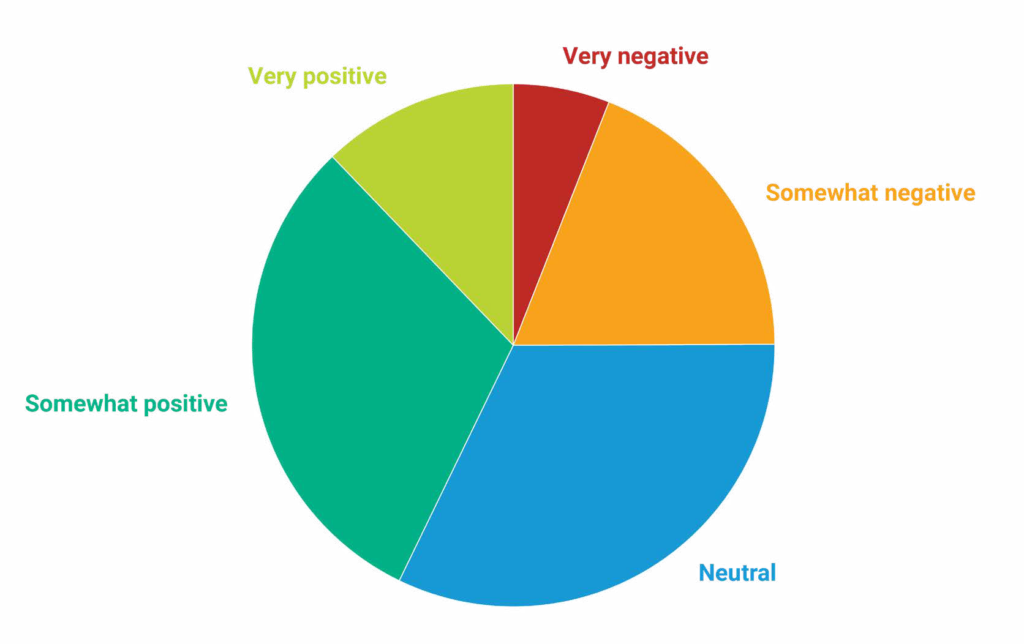
Image caption: Tenant economic outlook rating
Retail tenants show a more negative economic outlook than the overall average. Around 33% of retail respondents report a negative outlook (compared to 24% across all sectors) indicating heightened concern about trading conditions. Neutral sentiment remains high at 32%, while positive sentiment is comparatively muted, with 25% somewhat positive and only 8% very positive. This suggests that retail confidence is under sustained pressure, with limited optimism about short term improvement.
Mixed use tenants are strongly neutral with 37% reporting a neutral outlook, above the all sector benchmark. However, this sector also shows the highest share of very positive sentiment, at 17%, compared to 12% overall. This split highlights uneven performance within mixed use environments, where confidence is closely linked to asset level execution.
Office tenants are the most confident sector overall. Nearly 39% report a somewhat positive outlook, significantly higher than the 31% all sector average, while only 2% report a very negative outlook. Neutral sentiment is 34%, indicating cautious optimism rather than exuberance.
Industrial tenants also show consistently positive confidence, with 33% somewhat positive and 14% very positive, both well above the overall averages. Negative sentiment remains contained at 22%, supporting the view that industrial tenants are comparatively resilient.
Overall, sectors with weaker economic confidence – particularly retail – are more exposed to renewal risk, while office and industrial tenants show stronger underlying business confidence.
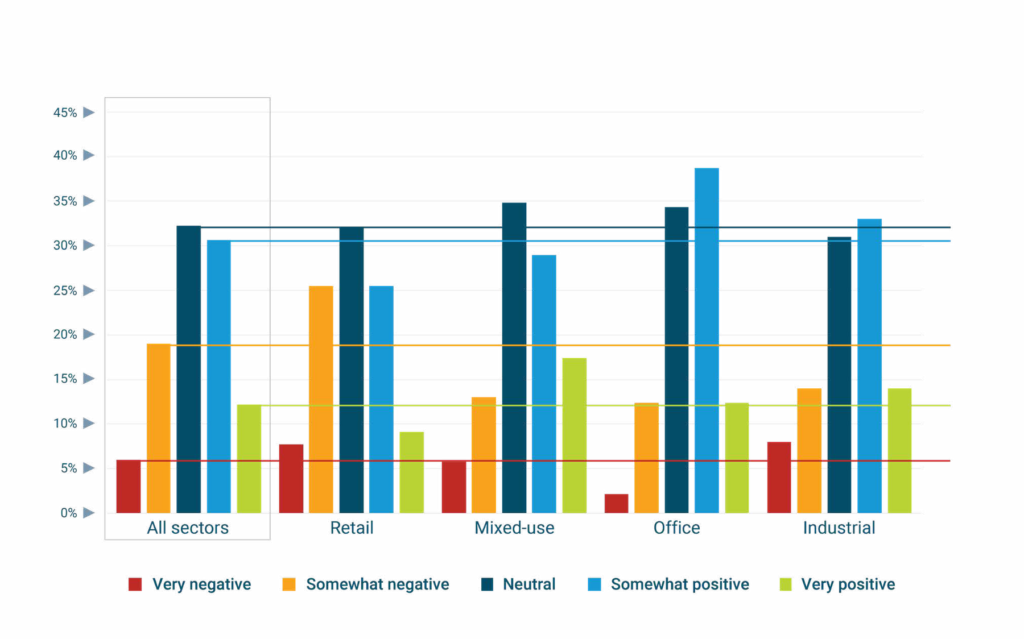
Image caption: Economic outlook by sector – tenant business confidence distribution
Growth constraints
When tenants were asked to identify the three biggest barriers preventing their businesses from growing that are not related to their leased premises, the results point to macro economic pressure and rising cost structures as the dominant constraints. Growth challenges are primarily being shaped by the external environment rather than by operational or logistical issues within individual businesses.
Economic growth emerges as the single biggest barrier, cited by 22% of respondents. Weak demand, constrained consumer spending and subdued confidence are limiting tenants’ ability to expand turnover, invest or take on additional space. Even well run businesses report that their growth ambitions are being held back by the broader economic climate.
The second most significant barrier is utility costs, selected by 17% of tenants. Escalating electricity and water costs are placing sustained pressure on operating margins, particularly for retail, industrial and service oriented occupiers. These costs are viewed as unavoidable, difficult to forecast and increasingly disconnected from actual usage, directly reducing funds available for reinvestment and growth.
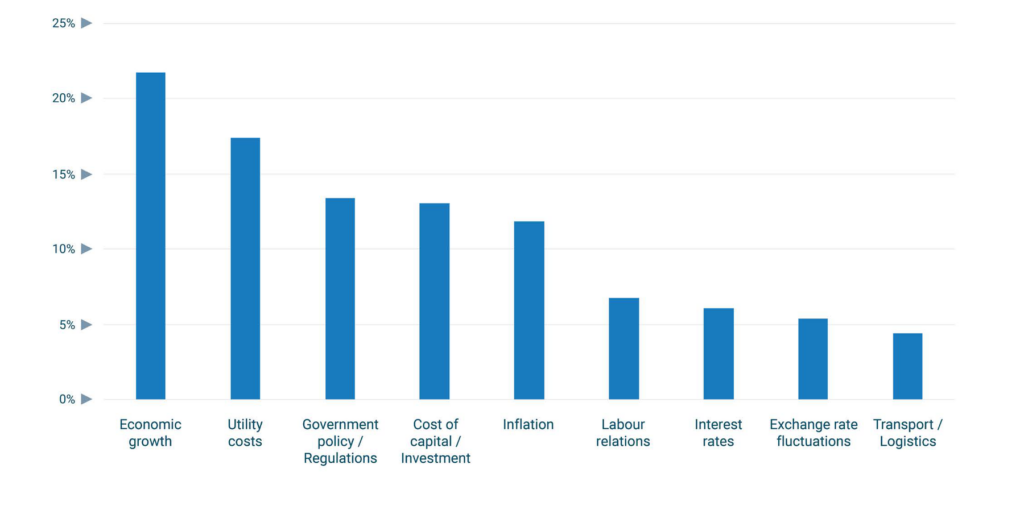
Image caption: Top external barriers preventing tenant business growth
The third most significant constraint is government policy and regulation, identified by approximately 13% of respondents. Tenants reference regulatory complexity, compliance costs and policy uncertainty as factors that slow decision making, increase overheads and discourage longer term investment. For smaller businesses in particular, these burdens are seen as disproportionately restrictive to growth.
Surprisingly, at the opposite end of the spectrum, transport and logistics (4%) and exchange rate fluctuations (5%) rank as the least impactful growth barriers. While relevant to specific sectors, these issues are not viewed as primary growth constraints for the majority of commercial tenants, suggesting that most businesses have either adapted to them or are less directly exposed to them than to broader economic and cost pressures.
Overall, the results reveal that tenant growth potential is being constrained primarily by the economic environment and cost pressures, rather than by operational inefficiencies. This highlights the importance of affordability, cost transparency and supportive operating conditions to enable tenants to position their businesses for growth.
Many tenants have been slow to adopt technology which could address some of the internal cost pressures and utility cost management and position them for future growth when economic conditions improve.
Tenant growth barriers
This section explores the key obstacles limiting tenants’ ability to grow, invest and plan future space needs, providing insight into how economic conditions and location related factors influence expansion decisions.
The results show that cost pressures and demand constraints dominate growth challenges. Cost of rent is the most significant barrier, cited by around 21% of tenants, confirming that affordability remains the primary constraint on expansion. High rentals are limiting reinvestment, hiring and appetite for additional space.
This is followed by market demand (14%), reflecting subdued trading conditions and cautious consumer spending which continue to suppress revenue growth and confidence. Regulatory or compliance burdens and access to finance (both 12%) form the next tier of constraints, highlighting how compliance complexity and limited funding availability restrict tenants’ ability to scale. Access to skilled labour varies by sector, but overall, around 8% of tenants rated labour as a barrier to growing their businesses.
At the lower end, poor infrastructure or utilities (6%), other factors (5%) and technology impact (4%) are cited least frequently, indicating that while relevant, these are not the primary barriers to growth for most tenants compared to affordability and economic conditions.
Overall, the findings show that tenants’ future growth is primarily constrained by rental costs, demand conditions and access to capital – factors that directly shape future space requirements and renewal decisions – rather than by operational or technology limitations.
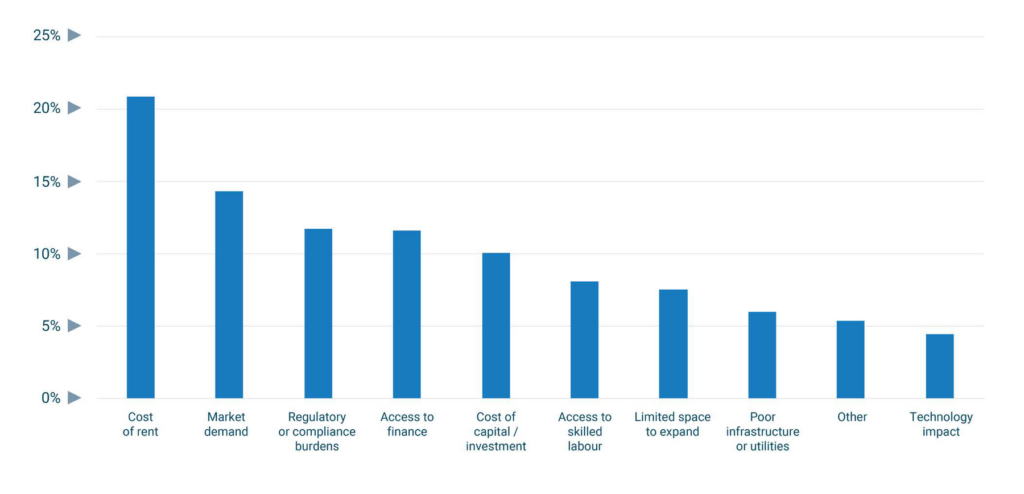
Image caption: Biggest internal barriers preventing tenant business growth
Internal barriers to growth
The survey revealed a subset of growth barriers concerns focused on internal business capability and strategic readiness, particularly among smaller, owner managed enterprises. These include:
- Operational efficiency and skills constraints, including limited management capacity, staffing shortages and difficulty upskilling employees.
- Technology adoption readiness, where tenants acknowledge the need for digital tools but struggle with execution, prioritisation or internal expertise.
- Business model adaptation, particularly in retail and service sectors facing online competition, changing consumer behaviour or market saturation.
- Capital allocation decisions, with some tenants indicating that growth is constrained by conservative reinvestment strategies or competing personal and business financial pressures.
While these challenges primarily impact tenants, they are often exacerbated by external cost pressures. Many tenants indicate a willingness to improve operations or adopt technology if costs, risks and complexity can be reduced, suggesting scope for enablement rather than resistance.
Candid tenant feedback
This section is based on an open field comment section included in the survey, asking tenants what their biggest pain points are.
1. Rental affordability and escalations
This is the most commonly raised pain point in the open field section. Tenants cite high base rentals and aggressive escalations as their primary source of strain. Many report that rent increases are out of sync with turnover growth, inflation and broader economic conditions, leaving little room for reinvestment or expansion. Common concerns include:
- Rent consuming a disproportionate share of revenue
- Escalations applied mechanically, regardless of performance
- Lack of affordability relief during downturns or disruptions
- Feeling locked in to unsustainable rental structures.
2. Operating costs and billing transparency
High and frequently unclear operating costs, particularly for utilities, are a significant source of frustration. These costs are widely viewed as uncontrollable, compounding rental pressure. Tenants mentioned:
- Unpredictable electricity and water charges
- Poor visibility on how shared or pro rata costs are calculated
- Perception that operating costs are used to supplement rental income
- Difficulty disputing or reconciling bills.
3. Landlord engagement, communication and responsiveness
Many tenants are dissatisfied with the quality of their landlord or managing agent interaction. Where engagement is strong, tenants explicitly associate it with greater stability, trust and willingness to renew. Key issues include:
- Slow responses to maintenance or billing queries
- Feeling ignored or dismissed when raising concerns
- Enforcement focused communication rather than partnership
- Limited access to decision makers.
4. Maintenance, infrastructure and asset condition
Many comments relate to poor maintenance and infrastructure reliability, particularly in older buildings or secondary locations. These issues directly affect customer experience, staff morale and operational continuity. Pain points include:
- Delayed or inadequate maintenance
- Poor condition of common areas, ablutions, lifts, and parking
- Power, water, leaks, or security issues disrupting operations
- Maintenance responsibilities are being pushed onto tenants.
5. Foot traffic, marketing and location performance
Retail and mixed use tenants frequently raise concerns about declining foot traffic and weak landlord led marketing. Weak location performance is often linked to reduced confidence in renewing or expanding. Common themes include:
- Empty shops and reduced centre vibrancy
- Limited visible marketing despite levies
- Poor tenant mix decisions
- Heavy reliance on tenants to self generate demand.
6. Economic, regulatory and external pressures
Tenants also mentioned broader forces beyond the control of landlords which intensify property related challenges. While acknowledged as external, frustration increases where property costs and inflexibility amplify these pressures. These challenges include:
- Weak economic growth and reduced consumer spending
- High interest rates and limited access to finance
- Rising labour, fuel and compliance costs
- Crime, urban decay and deteriorating municipal services.
Overall, the feedback from respondents reveals the growth constraints tenants face: economic pressure, rising occupancy costs and limited flexibility. Combined, these issues undermine their confidence and sustainability. Affordability, transparency and maintenance quality are all key concerns. Genuine landlord partnership are essential factors to alleviate pressure, ensure occupancy and enable long-term growth and lease renewals.
Business performance
This question assessed how tenants’ businesses performed over the past year, providing critical context for understanding confidence, affordability and future space decisions. The results reveal a fragile environment, where stability is common but strong growth remains limited with a significant number of tenants under pressure.
Overall performance is heavily skewed toward stagnation and mild decline. The largest group of tenants (28%) report that their business performance has been stable, indicating resilience but limited momentum. This suggests many businesses are focused on maintaining operations rather than expanding, hiring or investing.
However, this stability is accompanied by significant downside pressure. A concerning 42% of tenants report declining performance with 24% experiencing a slight decline and 18% reporting a significant decline. This shows that a significant number of tenants are operating in a stressed environment, where revenue softness and rising costs are eroding margins and growth confidence.
On the positive side, 29% of tenants reported growth, although this growth was predominantly moderate rather than strong. Moderate growth was reported by 24% of respondents, reflecting pockets of resilience and selective expansion, often tied to sector, location or business advantages. Only 5% report strong growth, revealing how rare robust expansion has been over 12 months.
Taken together, the results paint a picture of three types of tenants: a significant group under pressure, a large cohort holding steady and a relatively small minority achieving strong growth. This performance profile highlights why affordability, flexibility and supportive asset management are critical, particularly as many tenants look to first stabilise before considering expansion or longer term commitments.

Image caption: Tenant business performance over the past 12 months
The rental escalation ceiling
Tenant tolerance for rental escalations is clearly anchored at the lower end of the scale, a reminder of how important affordability is in sustaining occupier stability. More than half of respondents (50.9%) say that escalations of 1-4% per annum are acceptable, establishing this price band as the dominant market expectation for sustainable rental growth.
A further 32.1% of tenants will accept escalations in the 5-7% range, suggesting that CPI linked or modestly above inflation increases are workable for nearly a third of respondents, particularly where location quality, operational support or asset performance justify the increase.
Notably, 10.7% of respondents won’t accept any escalation, revealing either a segment of tenants under acute cost pressure or where expectations between the landlord and tenant is misaligned to the point where perceived business performance is linked to the premises, where any increase risks affordability stress.
Tolerance drops sharply beyond this point, with only 5.6% accepting escalations of 8-10%, with negligible acceptance for increases above 10%. This indicates a clear market ceiling for escalation expectations and signals a growing resistance to aggressive fixed uplifts.
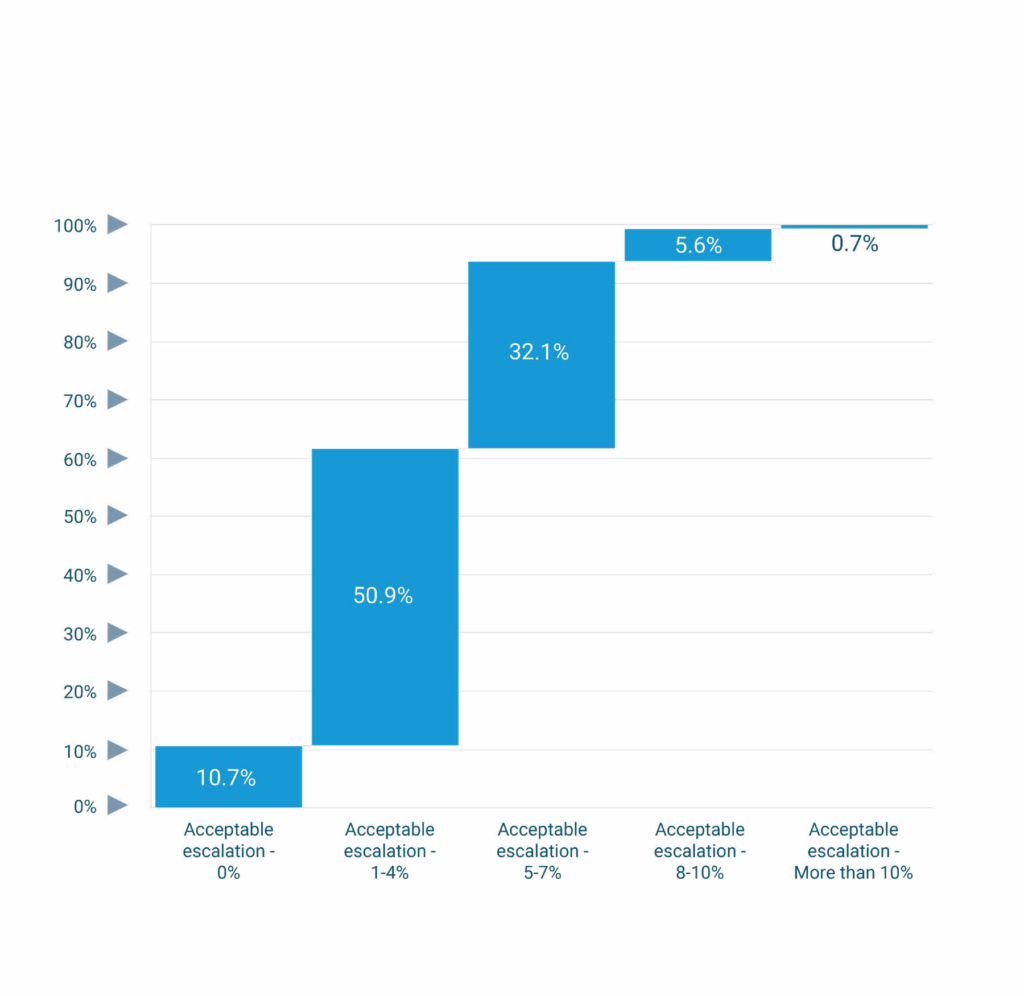
Image caption: Acceptable annual rental escalations for commercial occupiers
Retention forecast
The data suggests a close relationship between escalation tolerance and the probability of lease renewal, particularly when viewed alongside the all-sector renewal sentiment. While 54% of tenants indicate that they are likely (32%) or very likely (22%) to renew, a significant 27% remain undecided and 19% say they are unlikely or very unlikely to renew.
Renewal probability is highest where proposed increases fall within the 1-4% range and remains relatively resilient up to 5-7%. However, escalation expectations above this level increasingly overlap with the undecided and unlikely renewal cohorts, indicating a heightened risk of churn when rental growth outpaces tenant affordability or trading performance.
The data shows that the rental escalation strategy plays a crucial role in driving successful lease renewals. In a market characterised by cautious confidence and rising operating costs, setting escalation levels that exceed what tenants can tolerate significantly increases the risk of non-renewal and steady default risk. As leases near their expiration, it is essential to align escalation expectations with current affordability levels, particularly within the 1-4% range and, to some extent, the 5-7% range. This approach will be key to maintaining occupancy rates, ensuring stable income and converting undecided tenants into committed renewals.
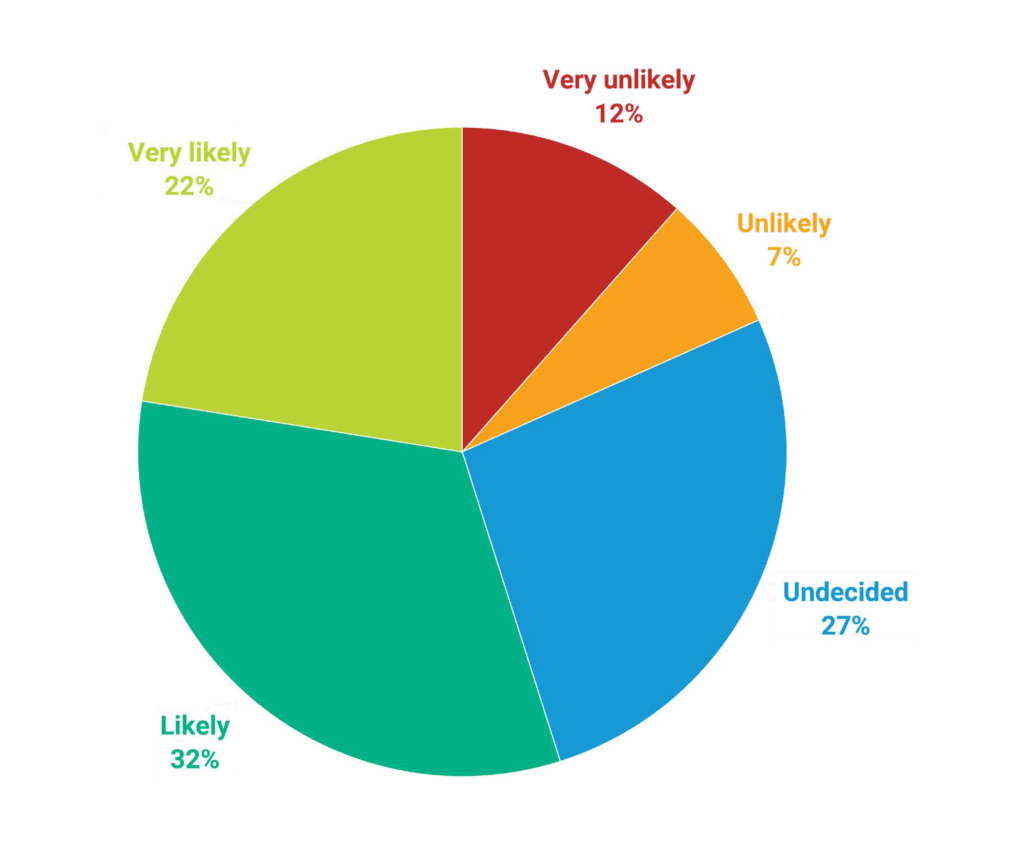
Image caption: Renewal intent of commercial real estate occupiers
Renewal risk analysis
Tenant feedback indicates a market that is not in crisis but is under growing strain. Overall satisfaction remains broadly balanced, yet the underlying sentiment points to increasing renewal risk if current pressures are not actively managed. Around 40% of tenants describe themselves as satisfied, 38% as neutral and 22% as dissatisfied. The neutral group are the cohort that landlords should be most concerned about. These tenants are neither unhappy nor loyal; they are watching costs closely and are most likely to leave at renewal if conditions deteriorate.
Rental escalation is the strongest pressure shaping this behaviour. Most tenants report annual escalations in the 1-7% range, with the largest share falling between 1-4% and 5-7%. Escalations above 8% are relatively uncommon, yet rental costs remain the most frequently cited challenge in the survey. This indicates a clear shift in tolerance. What has historically been regarded as market standard escalation is now straining, particularly when tenant turnover, foot traffic or margins are flat. For tenants, rental increases are increasingly felt alongside rising utilities and operating costs rather than in isolation.
The economic and business outlook significantly influences how tenants respond to these increases. About 25% of respondents express a negative outlook, just over 30% are neutral and approximately 43% remain positive. This distribution closely mirrors satisfaction levels. Tenants who feel pessimistic about the economy show far lower tolerance for escalation and are quicker to reassess their space needs. Tenants with a positive outlook are more resilient and better able to absorb moderate increases, provided they continue to see value in their premises.
When these factors are considered together, renewal risk becomes clearer. The highest risk group is not necessarily the most dissatisfied tenants, but rather those who are neutral in their satisfaction, facing escalations of 5% or more, and are uncertain or negative about their economic outlook. These tenants are often quiet, compliant and current on payments, yet structurally positioned to exit at renewal if conditions do not improve. Dissatisfied tenants represent a smaller but more immediate risk, while satisfied tenants with positive outlooks are comparatively stable unless escalation becomes abrupt or inflexible.
Of particular interest to landlords and investors is the fact that renewal risk, according to the survey data, is building quietly. Even a 15-25% share of higher risk tenants can materially affect vacancy levels, reletting costs and income stability. Uniform escalation strategies may protect short term income, but they increase medium term risk if they are not aligned with tenant realities. For tenants, the findings stress the importance of early engagement and transparency. Where landlords demonstrate flexibility and responsiveness, tolerance for cost pressure improves.
The central message of the survey is that renewal outcomes are no longer driven primarily by lease length or space size but by perceived value, affordability and confidence in the trading environment. Neutral sentiment is not a safe holding pattern but rather an early warning signal. Landlords who identify and engage with cost sensitive and economically uncertain tenants ahead of renewal are better positioned to protect occupancy and income continuity, while tenants benefit from earlier, more constructive renewal conversations.
The survey points to a market where proactive engagement and differentiated renewal strategies are becoming essential. Renewal quality now matters as much as escalation level. Managing sentiment early is increasingly the difference between stable income and avoidable vacancy.
Tech adoption as a growth catalyst
Across all sectors, technology adoption over the past 12 months has delivered broadly positive outcomes, with a clear majority of tenants reporting either some or a significant positive impact on their businesses. At an all sector level, around two thirds of tenants indicate positive impact, reinforcing the role of technology as a key enabler of operational resilience, efficiency and customer engagement in a challenging trading environment.
Office and industrial tenants show the strongest positive outcomes, with a comparatively high number reporting that new technologies have had a positive impact. In these sectors, technology investments are typically focused on workflow automation, systems integration, data management and operational efficiency, which translate more directly into measurable productivity gains and cost control. These tenants appear better positioned to convert technology spend into tangible business benefits.
Retail tenants also report predominantly positive outcomes, though the impact skews toward modest gains rather than transformative change. This reflects the practical application of technology in retail – such as point of sale upgrades, online sales channels, payment solutions and customer engagement tools – which tend to support revenue continuity and operational stability rather than driving step change growth. Retail’s relatively higher ‘no impact’ and ‘not sure’ responses suggest uneven execution and varying returns depending on tenant size, digital maturity and location quality.
Mixed use environments generated a more polarised response, with strong positive outcomes for some tenants alongside a higher proportion of uncertainty. This reflects the diversity of tenant profiles within mixed use assets, where the effectiveness of technology adoption is closely linked to asset level infrastructure, connectivity and management support.
Overall, the data indicates that where technology is adopted with a clear purpose and operational alignment, tenants are seeing real benefits, particularly in sectors with more structured operating models.
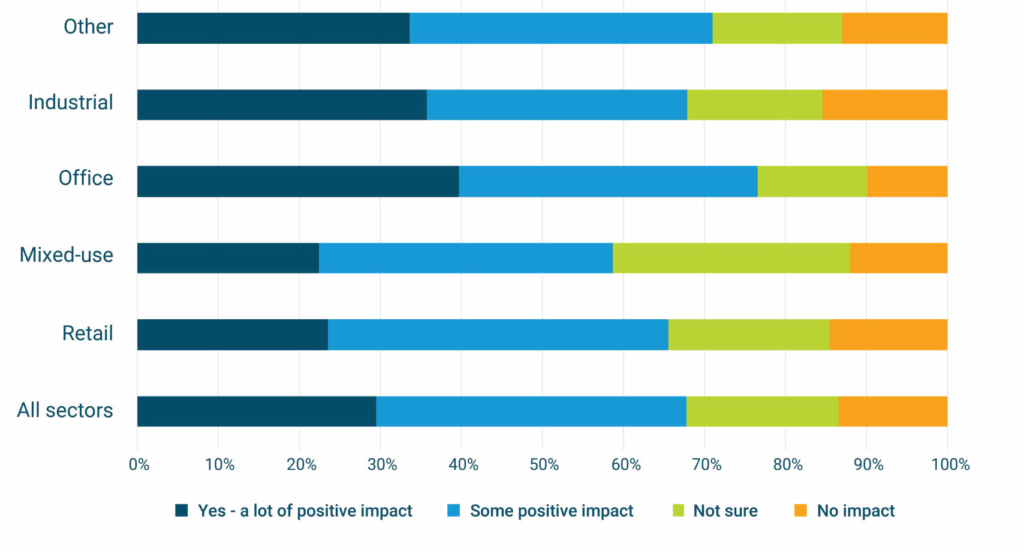
Image caption: Impact of new technology adoption on tenant business
While the benefits of technology adoption are evident, structural and perceptual barriers continue to limit uptake among a meaningful portion of the commercial tenant population.
The single largest barrier is uncertainty about value, with approximately one third of tenants revealing they are unsure how technology would add value to their business. This points to a knowledge and relevance gap rather than outright resistance. Many tenants – particularly smaller or owner managed businesses – struggle to connect available solutions to their specific operational challenges or financial outcomes.
High cost is the second most significant constraint, cited by roughly a quarter of respondents. In an environment of rising rentals, utilities and input costs, upfront investment in new systems is often deprioritised, even where long term benefits are acknowledged. This is especially relevant for retail and smaller commercial tenants operating with tight margins and limited access to capital.
An additional layer of friction arises from gaps in awareness and capability. Approximately 15% of tenants report a limited awareness of available solutions, while just over 10% say that staff skills and training constraints pose challenges. What these responses reveal is that the hurdles to adoption are not solely financial; many tenants also lack the internal capacity to implement, manage or derive value from new technologies.
Other technical barriers, such as difficulty integrating with existing systems and data migration or security concerns, are also mentioned but are considered comparatively less material. This suggests that for most tenants, the challenge lies earlier in the decision making process rather than at the implementation stage.
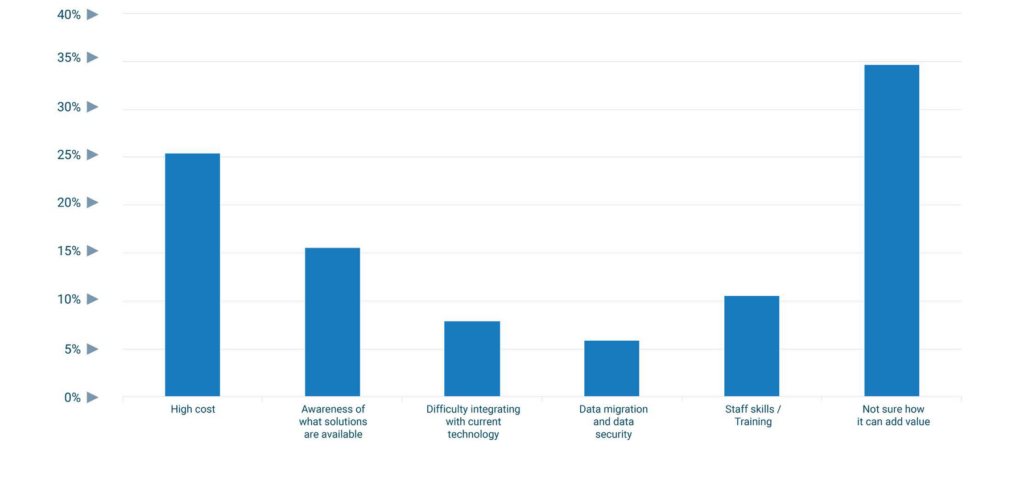
Image caption: Barriers to technology adoption among tenants
How landlords are constraining tenant growth
A dominant theme across the open text responses is the role of landlord practices in constraining tenant growth, particularly through cost, flexibility and asset management. Key landlord controlled barriers include:
- Rental affordability and escalation structures, with repeated references to rent increases outpacing turnover growth and inflation, eroding profitability and limiting reinvestment capacity.
- High and vague operating costs, especially utilities, municipal charges and shared services, are often described as unpredictable, poorly explained or disproportionate to the value received.
- Inflexible lease terms, including limited early exit options, aggressive enforcement and lack of accommodation during trading downturns or refurbishment periods.
- Maintenance and infrastructure shortcomings, such as poor building upkeep, unreliable utilities, inadequate security and slow response times, directly impact customer experience and staff productivity.
- Limited landlord engagement and support, with many tenants describing a one sided relationship focused on rent extraction rather than partnership, collaboration or long term sustainability.
- Insufficient marketing and foot traffic generation, particularly in retail and mixed use assets, where tenants feel they carry the full burden of attracting customers despite paying marketing or operating levies.
These issues are repeatedly linked to reduced confidence to expand, hire or invest, and in some cases result in decisions to downscale, relocate or exit leases altogether.
While the macro-environment sets the stage, the landlord’s response to these pressures – through lease flexibility and asset upkeep – determines whether a tenant survives the downturn or seeks alternative premises.
The impact of the wider ecosystem
Beyond tenant and landlord actions, respondents consistently point to structural macro economic and regulatory constraints that shape the operating environment. The most frequently cited external barriers include:
- Weak economic growth and declining consumer spending are limiting revenue growth across most sectors.
- High interest rates and the cost of capital restrict access to finance and make expansion or equipment investment less viable.
- Rising utility and municipal costs, particularly electricity and water, are often seen as unpredictable and misaligned with actual usage.
- Regulatory and compliance burdens, including labour regulations, B-BBEE requirements and sector specific compliance costs that disproportionately affect smaller businesses.
- Crime, urban decay and infrastructure deterioration, especially in CBD and older node locations, are impacting customer footfall, staff safety and insurance costs.
- Policy uncertainty and governance challenges undermine investor confidence and delay long term planning.
These macro factors are widely recognised by tenants as being outside the immediate influence of landlords, yet the data shows their impact is magnified when combined with rigid lease structures and escalating occupancy costs.
Conclusion
The TPN 2026 Voice of the Commercial Tenant survey reveals a market under cost pressure, where tenant satisfaction is currently balanced but increasingly fragile. While 40% of tenants report being satisfied with their premises, the high concentration of neutral sentiment (38%) suggests that a large segment of the market is at risk of churn should economic conditions or rental structures become untenable.
The data confirms that the traditional market-standard escalation is facing a ceiling of resistance. With over 50% of tenants indicating that annual increases should ideally remain between 1% and 4%, there is a clear disconnect between historical lease structures and current business performance, where 42% of tenants report declining turnover. The primary threats to lease renewals are no longer just internal property issues, but a combination of high rental costs, escalating utility expenses and a lack of transparency in municipal billing.
What the survey ultimately reveals is that renewal outcomes are increasingly driven by a tenant’s perception of value and affordability. For the commercial property sector to remain resilient, the wider ecosystem must address these core pain points: rental flexibility, infrastructure reliability and proactive engagement. As renewal risk builds among neutral-rated tenants, the ability to interpret these sentiment signals will be the difference between maintaining occupancy and facing rising vacancies in the years ahead.